

Kevin Warsh’s speech last Friday in Jackson Hole was a good one. It was the speech he needed to give. Warsh opened with AI—100% human-written text, I checked. Then he turned to his arguments against forward guidance, his seven principles of monetary policy, and closed with a discussion of how he sees the economy now, including his first analysis of inflation data. Warsh came down from 30,000 feet and found firmer footing. The speech was true to Kevin Warsh, and it was the first time he sounded like a Fed Chair. That’s only the first step to being a good Chair, but an important one.
Clean up and bridge building
Warsh cleared up two areas of confusion from his July presser, ones that I have written about. First, he was clear on the target: “The Fed's price-stability objective of 2 percent, as measured by the personal consumption expenditures (PCE) price index, is a firm, fixed target.” Firm and fixed. That’s a much better answer than in July. Warsh also resolved confusion over the Fed’s tools. He set the balance sheet to the side for now, saying “short-term interest rates are the predominant tool to achieve the dual mandate.” So, if the Fed tightens this year, it’s the federal funds rate rising, not the balance sheet shrinking. None of this suggests Warsh is happy with the size of the balance sheet, but the speech carefully pushed reform ideas into the future and elevated the tried-and-true for the present. Playing the long game is the right way to pursue change at the Fed.
It was more subtle, but it was good to see Warsh building bridges to the Committee. Many picked up on the fact that Warsh started with a story about hiking, the literal in-the-Tetons kind, not the rate-increase kind. As I said, this was a Warsh speech. What grabbed my attention: the first name in the speech, part of the hiking story, was Don Kohn. I can’t think of another living person more widely beloved at the Fed, Committee and staff, past and present, than Kohn. I heard Kohn’s name and took a deep breath. Warsh’s speech was going to be good. Building a consensus is hard work, and his speech was unlikely to have repaired all the damage of the presser.
It was a good speech. To be clear, I disagreed with several parts, above all Warsh's calls for a "quieter" Fed. Now there's enough substance for a good family fight.
Inflation, inflation, inflation.
What will matter most to people is the closing of Warsh’s speech: an assessment of the economy today. That’s a critical starting point when the FOMC meets in two weeks to decide whether to raise rates or to remain on hold.
Warsh first shared the Committee’s views, including the reason for the hold, a welcome clean-up of the presser:
You may have read in the July minutes the unanimous view of the FOMC: Labor markets were stable, and output was solid. But inflation remained too high. A good majority of my colleagues and I thought the wiser course was to await new information in the intermeeting period—especially given possible developments in supply chains, investment flows, and geopolitics—before deciding whether a change in interest rate policy was advisable. And we expressed our joint readiness to act as circumstances might require. (Emphasis added.)
Then Warsh turned to his views:
For my part, today I am impressed by the overall performance of the economy, which appears to have strengthened. One indicator of strength is how well an economy holds up to shocks. On that score, both Main Street and Wall Street have been remarkably resilient.
He didn’t stop at the high level. He went through various parts of the economy: business capital expenditures, corporate profits, credit spreads, lending standards, housing, agriculture, consumer spending, and private domestic final purchases. It might not be the exact summary I would offer, but it was data-driven in a way that’s rare for Warsh and common for Fed Chairs.
On the employment side of the mandate, Warsh described the labor market as “stable” and “consistent with full employment.” Again, he marshaled the data: payrolls, the unemployment rate, initial unemployment claims, JOLTS, and slow growth in labor supply to make his argument.
On inflation, Warsh’s assessment was downbeat, positioning him closer to the Fed officials who have already said they want a hike than to those who have voted to hold:
But on the price-stability side of our mandate, the numbers are more concerning. The Fed’s preferred measure of inflation, the 12-month change in the PCE price index, stands at 3.7 percent, while the six-month change is 4.1 percent. The comparable measures from the consumer price index (CPI) are also elevated, as are the core measures of both PCE and CPI inflation. None of these measures are perfect, but they all tell a similar story: Inflation is running above our 2 percent target. So the Fed’s predominant focus right now should be on prices.
Importantly, Warsh does not seem impressed by the softer inflation prints recently:
And while this summer’s PCE and CPI readings were better than expected, they do not tell me that underlying trends have meaningfully improved.
After a nod to wages, which he does not view as a reliable signal of trend inflation, Warsh discussed the distribution of inflation:
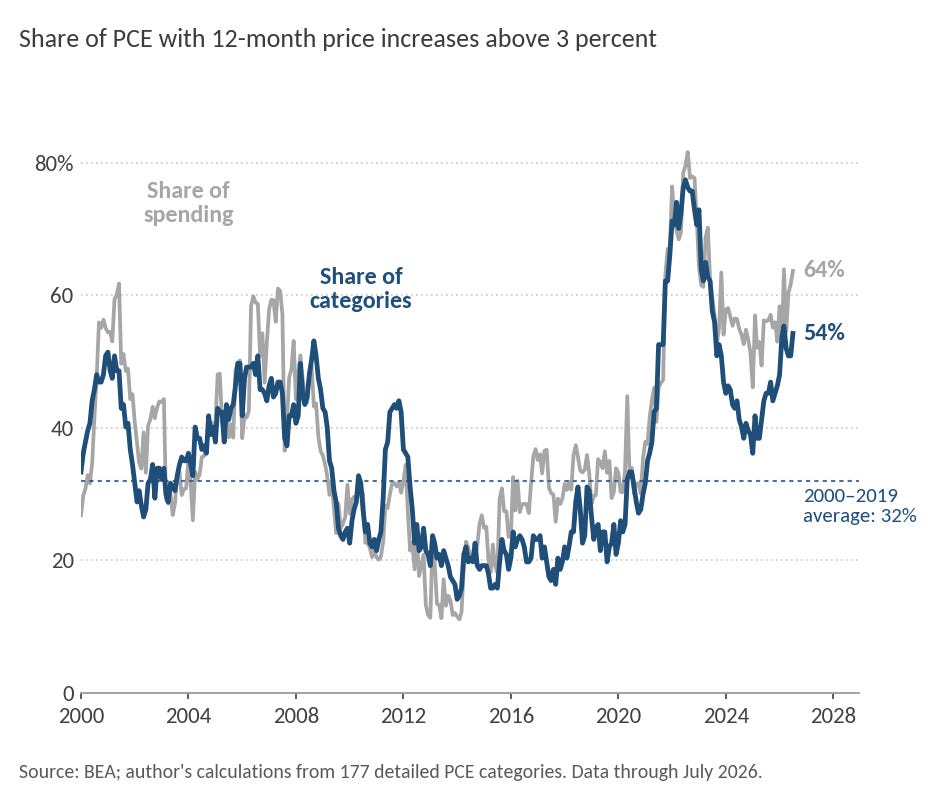
To try to gauge underlying inflation, I find it instructive to disaggregate the 199 individual components of the PCE price measure. Over the past 12 months, 54 percent of goods and services in the PCE basket showed price increases above 3 percent. This is well below the post-pandemic highs of about 77 percent, but it remains well above the level of 32 percent in the two decades that preceded the pandemic.
Breadth fits with his past references to median and trimmed mean measures. Warsh did not include a chart in the speech, but the one I made below replicates his share of categories with prices rising more than 3% (blue line). The share of spending counterpart (gray line) is even higher, because a few heavy categories, owners’ equivalent rent above all, sit over 3%. Headline inflation is elevated, and it's not a handful of outliers doing the work. The breadth is elevated, too.
Warsh flagged commodity prices and inflation expectations as factors to watch. He closed with accountability and a confidence test:
There is one signal nobody can miss: The responsibility for 65 months of sustained, elevated inflation sits squarely with the central bank. And that is where it belongs.
Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do. That’s our job . . . our mandate . . . and our charge to keep.
That is the question each FOMC member faces in September. Confident inflation is coming down soon with the federal funds rate where it is, then hold. If not, it's time to raise rates. Warsh did not share his verdict, nor the Committee's. That would have been the forward guidance he wants to dial back. But he shared his framework, and it's consistent with the July minutes. Now we wait for the remaining data and the FOMC's judgment.
In closing.
After Jackson Hole, Kevin Warsh is less of an enigma. We have more clarity on his views about monetary policy—some are traditional, and some are not. The FOMC will sort that out over the coming years. We also saw him take on the familiar role of a Fed Chair, narrating the economy with data and using them to set up the Committee’s deliberations later this month. The Jackson Hole speech doesn’t make the decision any easier, but it should help us rest easier about the process.
PS: It’s not just me. Puffi was also a fan of Warsh’s speech. She weighed in on Twitter Friday night.
I think "the proof of the pudding is in the eating". When he votes to raise rates in open defiance of Trump's view, then - and only then - will I think he has anything to applaud.
Claudia, thanks for your solid analysis. I wonder, though, if holding the Fed responsible for the extended period of above-target inflation, as Chair Walsh and many others do, is too simplistic. For at least some of the last 5.5 years, the Committee could have run a notably tighter monetary policy that would likely have brought inflation down more quickly. In my view, such tighter policy would have had adverse implications for the real economy. Given that the labor market and GDP look solid but not spectacular, and that there have been protracted negative supply shocks, I think policy tight enough to bring inflation down would most likely caused a recession. Indeed, I learned in school and in practice that monetary policy in the face of supply shocks is extraordinarily difficult.
Could the Committee have done better? Yes. But using monetary policy (i.e. demand management) more robustly would not have produced unambiguously better outcomes. There really is more than enough blame for persistently high inflation to go around: fiscal policy seems to have overshot, supply-chain issues were powerful inflationary factors, and more recently tariffs and immigration policy have contributed to still-elevated inflation. Moreover, immigration policy in particular has complicated interpretation of the unemployment and payroll employment data.
And, unlike the 1970s, inflation expectations remained fairly well anchored even with accomodative policy. I think that this suggests that the policy mistakes were not as bad as others have argued. It was incorrect, but not crazy, to believe that high inflation would prove to be very transitory.
I wish that the chair and other influential people would recognize that recent inflation cannot be explained by uncomplicated answers.