


A week from Friday, Kevin Warsh will deliver his first speech as Chair at the Fed’s Jackson Hole Symposium. The majestic backdrop of the Grand Teton is a world away from the Fed’s stuffy offices in DC, but the test will be the same as at every press conference: what does Warsh say? In today’s post, I offer perspectives on the first Jackson Hole speeches of the three previous Fed Chairs, what I want to hear from Warsh, and why a strong, credible Fed matters more than ever.
What’s in a Jackson Hole speech?
With the benefit of hindsight, a Fed Chair’s first speech at Jackson Hole has been a window into their economic worldview and their style as a central banker:
Ben Bernanke, August 25, 2006
“Global Economic Integration: What’s New and What’s Not?”
The economic historian. Bernanke’s first Jackson Hole speech on globalization is the most academic and least connected to monetary policy among the three recent Chairs, but it reveals the quality that proved critical to his tenure as Fed Chair: a deep appreciation for history. Keeping the Fed from repeating the mistakes of the Great Depression is central to his legacy. Bernanke’s speech also highlighted the interconnectedness in global markets—ties that would be severely tested in the Global Financial Crisis just a few years later.
Janet Yellen, August 22, 2014
“Labor Market Dynamics and Monetary Policy.”
The defender of the employment mandate. Over her long career at the Fed, Janet Yellen arguably did more than anyone to sharpen the Fed’s thinking around its maximum employment mandate. Her first Jackson Hole speech as Chair is an expansive treatment of the concerns at that time about the labor market and how to determine whether there is cyclical slack or a structural shortfall. In her trademark meticulous style, Yellen doesn’t just address the top explanations but goes through all of them. She concluded that the labor market recovery was incomplete. Yellen would lead the Fed to its first rate increase since the Great Recession more than a year later, and was already setting a tone of careful deliberation.
Jerome Powell, August 24, 2018
“Monetary Policy in a Changing Economy.”
The risk manager, skeptical of false precision. Powell’s first Jackson Hole speech ties most directly to monetary policy, specifically how to make policy decisions under uncertainty. He draws on theoretical concepts, like r-star, the neutral rate of interest, but warns that we cannot know them precisely. Powell also discusses the Brainard principle, which suggests taking small steps under uncertainty is best unless there is a risk of a trap that would be hard to escape. As Chair, Powell led the Fed through a series of unexpected events: a global pandemic, two trade wars, two major energy disruptions, and attacks on the Fed’s independence. He put the principles in his speech into action. The gradualism was costly with pandemic inflation, but the Fed’s aggressive pivot to hiking in 2022 produced the closest thing to a soft landing in generations.
I enjoyed re-reading those three speeches. Three people with different styles and facing different challenges. There’s no one formula for a strong Fed Chair.
What about Warsh?
So, what will Kevin Warsh’s entry into Jackson Hole history books be? That’s the question everyone is asking, but only one person knows the answer. And I hear he doesn’t like to talk.
The trait most likely to define Warsh’s Jackson Hole speech is his advocacy for regime change. Warsh has built his case for change for years by criticizing the Fed's models, data, and decisions. Now as Chair, he has set up task forces to make proposals. As the Financial Times notes, Warsh talks more about process (pink bars) than recent Fed Chairs who talked more about economic data (blue bars). That emphasis on process fits with someone devoted to regime change.
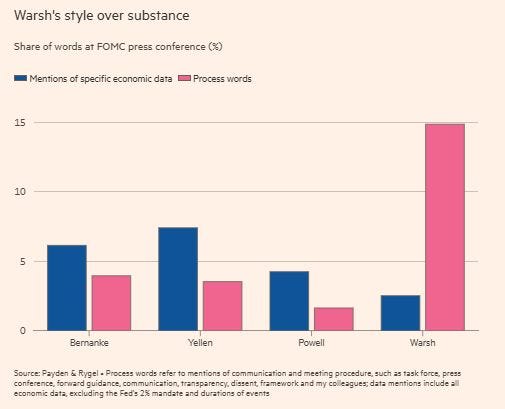
I don’t mind the process; it’s the lack of details that is endangering Warsh’s credibility. We have a clear sense of what Warsh doesn’t like at the Fed, but very little sense of what he’s proposing as a replacement. His Jackson Hole speech is an opportunity to bring depth to his vision for process improvements. Pick any part of his regime change and defend it. There are many options: He can explain why he believes financial markets are the most important source of information for the Fed, what he means by a new Treasury-Fed Accord, or why he thinks reducing the balance sheet is currently an alternative to a funds rate increase. It’s time to come down from 30,000 feet.
Keeping it in perspective.
Warsh’s Jackson Hole speech is about more than Warsh; it’s about the Fed as a credible institution. Every Fed Chair is tested, and for decades they have risen to the challenge. The stakes are higher now, with the White House openly pressuring the Fed.
In a recent HFR podcast, I discussed the risk of fiscal dominance, including Kevin Warsh’s call for a new Treasury-Fed Accord. There is a benign interpretation: a large Fed balance sheet and a large federal debt require the two to talk more. And there is a less benign one:
There is a less benign version where you have a lot more coordination between the Treasury and the Fed, where the Treasury might actually be giving marching orders to the Fed. The Treasury, in helping support the yen, was able to use tools that the Treasury itself had, but Secretary Bessent had pointed out that if the Fed raised the cap on their facilities, this could do even more. The Treasury has tools to do interventions. The Fed’s got bigger tools. If you get in a place where we’re handing the keys of the Fed’s balance sheet over to the Treasury to say “get interest rates low,” because they want to do more borrowing, that’s a real inflation risk. That’s not a history we want to repeat. This was exactly one of those cases where Warsh just throws something out there that could mean a lot of different things, but there’s some real risk there.
… A big overarching label for it would be fiscal dominance, so that the fiscal authority, White House, Treasury, they’re the ones calling the shots on monetary policy … There’s a lot in the institution at the Fed that protects the Fed from having this happen. But the reality, the backdrop with the government debt as large as it is, the incentives are really there. So, as I said, a risk. Not my base case, not where I think we’re headed, but there’s just been actions by Treasury that make me concerned that it could bleed over into the Fed. And some of Warsh’s messaging hasn’t been as clear as I’d want. We’re turning the first few pages of the fiscal dominance book. We’re not far into it, but I think it’s a real risk and certainly should be a risk for anyone in bond markets.
The rest of the conversation covers labor markets, housing, and Warsh and Fed culture. Audio and transcript here.
In closing.
I am looking forward to Warsh’s Jackson Hole speech. I expect to learn more about his thinking. I may not agree with his arguments, but I really want to hear them. His 30,000-foot claims and catchy slogans leave too many blanks. So far, Warsh is a bit of a Rorschach test. His critics read the worst into the blank spaces and his supporters the best. I just want to know who Kevin Warsh is and how his regime-change ideas would allow the Fed to better serve the American people.
If he continues on the path he's been on, I suspect Warsh will spout his usual meaningless (mostly) platitudes that can be read into any number of ways. He'll continue to be a Rorschach test, while trying to sneak in the regime's agenda wherever he can. I hope I'm wrong, but I'm not optimistic.
Thank you for the historical context and policies of the previous FED CHAIRS! The historical events of the first 25 years of this century have presented extremely difficult challenges for the FED and I have no issues with the Policy Decisions of the Fed prior to Warsh. If his words and actions are not precise then outcomes are not clear and clarity is badly needed in these challenging times. Btw, really liked the picture!