

It's Fed Week, even if headlines from the Middle East and on AI are stealing some attention. They should. Those stories also drive the inflation risks the Fed is responding to. Wednesday, the Federal Open Market Committee is highly likely to raise the federal funds rate by a quarter point. Last week, I explained why I favor the increase. In a survey of former Fed officials and staff, twenty-nine, including me, called for a rate increase versus one who wanted to stay on hold. Market pricing suggests a 90%+ chance of an increase. The decision is the first step; the Fed's explanation and guidance about future policy will be critical.
Modest rate hikes have a modest goal.
If the Fed raises rates, the explanation is critical for accountability. The Fed has been on hold since January. What changed, and why now? It also sets expectations. What does the Fed expect a rate increase to accomplish, and how much more does it expect to do?
Supply shocks like tariffs and energy have been a reason to hold, but not indefinitely. As I explained on Bloomberg last week, take energy shocks as an example: the Fed should not chase energy prices. The Fed is not trying to bring gasoline prices down with higher rates. It could, but at too high a price: massive demand destruction and employment losses. Instead, the Fed needs to contain the spillovers into non-energy prices, a risk that grows the longer energy prices stay elevated. More than six months of higher energy costs are now in the economy, and they have to go somewhere. Businesses either raise consumer prices to cover the costs or absorb them in tighter profit margins. By taking a little demand out of the economy, a modest rate increase can push more of those costs into margins and less into consumer prices.
That might sound like a no-brainer for the Fed: raise rates, keep inflation under control. But compressed margins put paychecks at risk. Squeezed businesses hire less and give smaller raises. Warsh has questioned whether there is a tradeoff between the Fed's employment and inflation goals, but it's hard to see how pulling demand out of the economy leaves the labor market untouched. Context matters, of course: profit margins have been solid, and the rate increases are likely to be modest. A rate hike may be the best policy now, but it's nothing to celebrate. It's costly medicine.
It’s also worth the Fed explaining what is not a problem right now. Longer-run inflation expectations, whether from household surveys or market pricing, have been fairly stable, and the labor market shows no signs of overheating. In 2022, when the Fed began its last hiking cycle (more than five percentage points in total), both were real concerns. Raising rates is not urgent. There is still a case to make for a hold, and raising rates dramatically is far from the base case.
Caution is warranted. A quarter-point increase now, with a signal of another hike or two if conditions warrant, is appropriate. A modest hike is insurance that the disinflation from supply-side healing is enough, not the Fed trying to engineer it by crushing demand.
Taking politics out of the rate decision is the only option.
Some commentators have argued that the Fed won’t raise rates this week, since the midterm elections are fast approaching and a hike would anger the President. It’s true that President Trump wants lower rates. Over the weekend, he reiterated his threat to cut off trade with “some countries” if the Fed does not cut, only the latest in a long string of attacks from the White House. The pressure campaign has led even defenders of Fed independence, like Harvard professor Ken Rogoff, to argue that the Fed should hold off on rate hikes until after the election.
In my Bloomberg Opinion piece last week, I argued that Rogoff’s advice is bad advice, and the best case against it is Rogoff’s own early-career research on why a central banker’s inflation-fighting credibility matters. Credibility is won or lost in high-pressure moments.
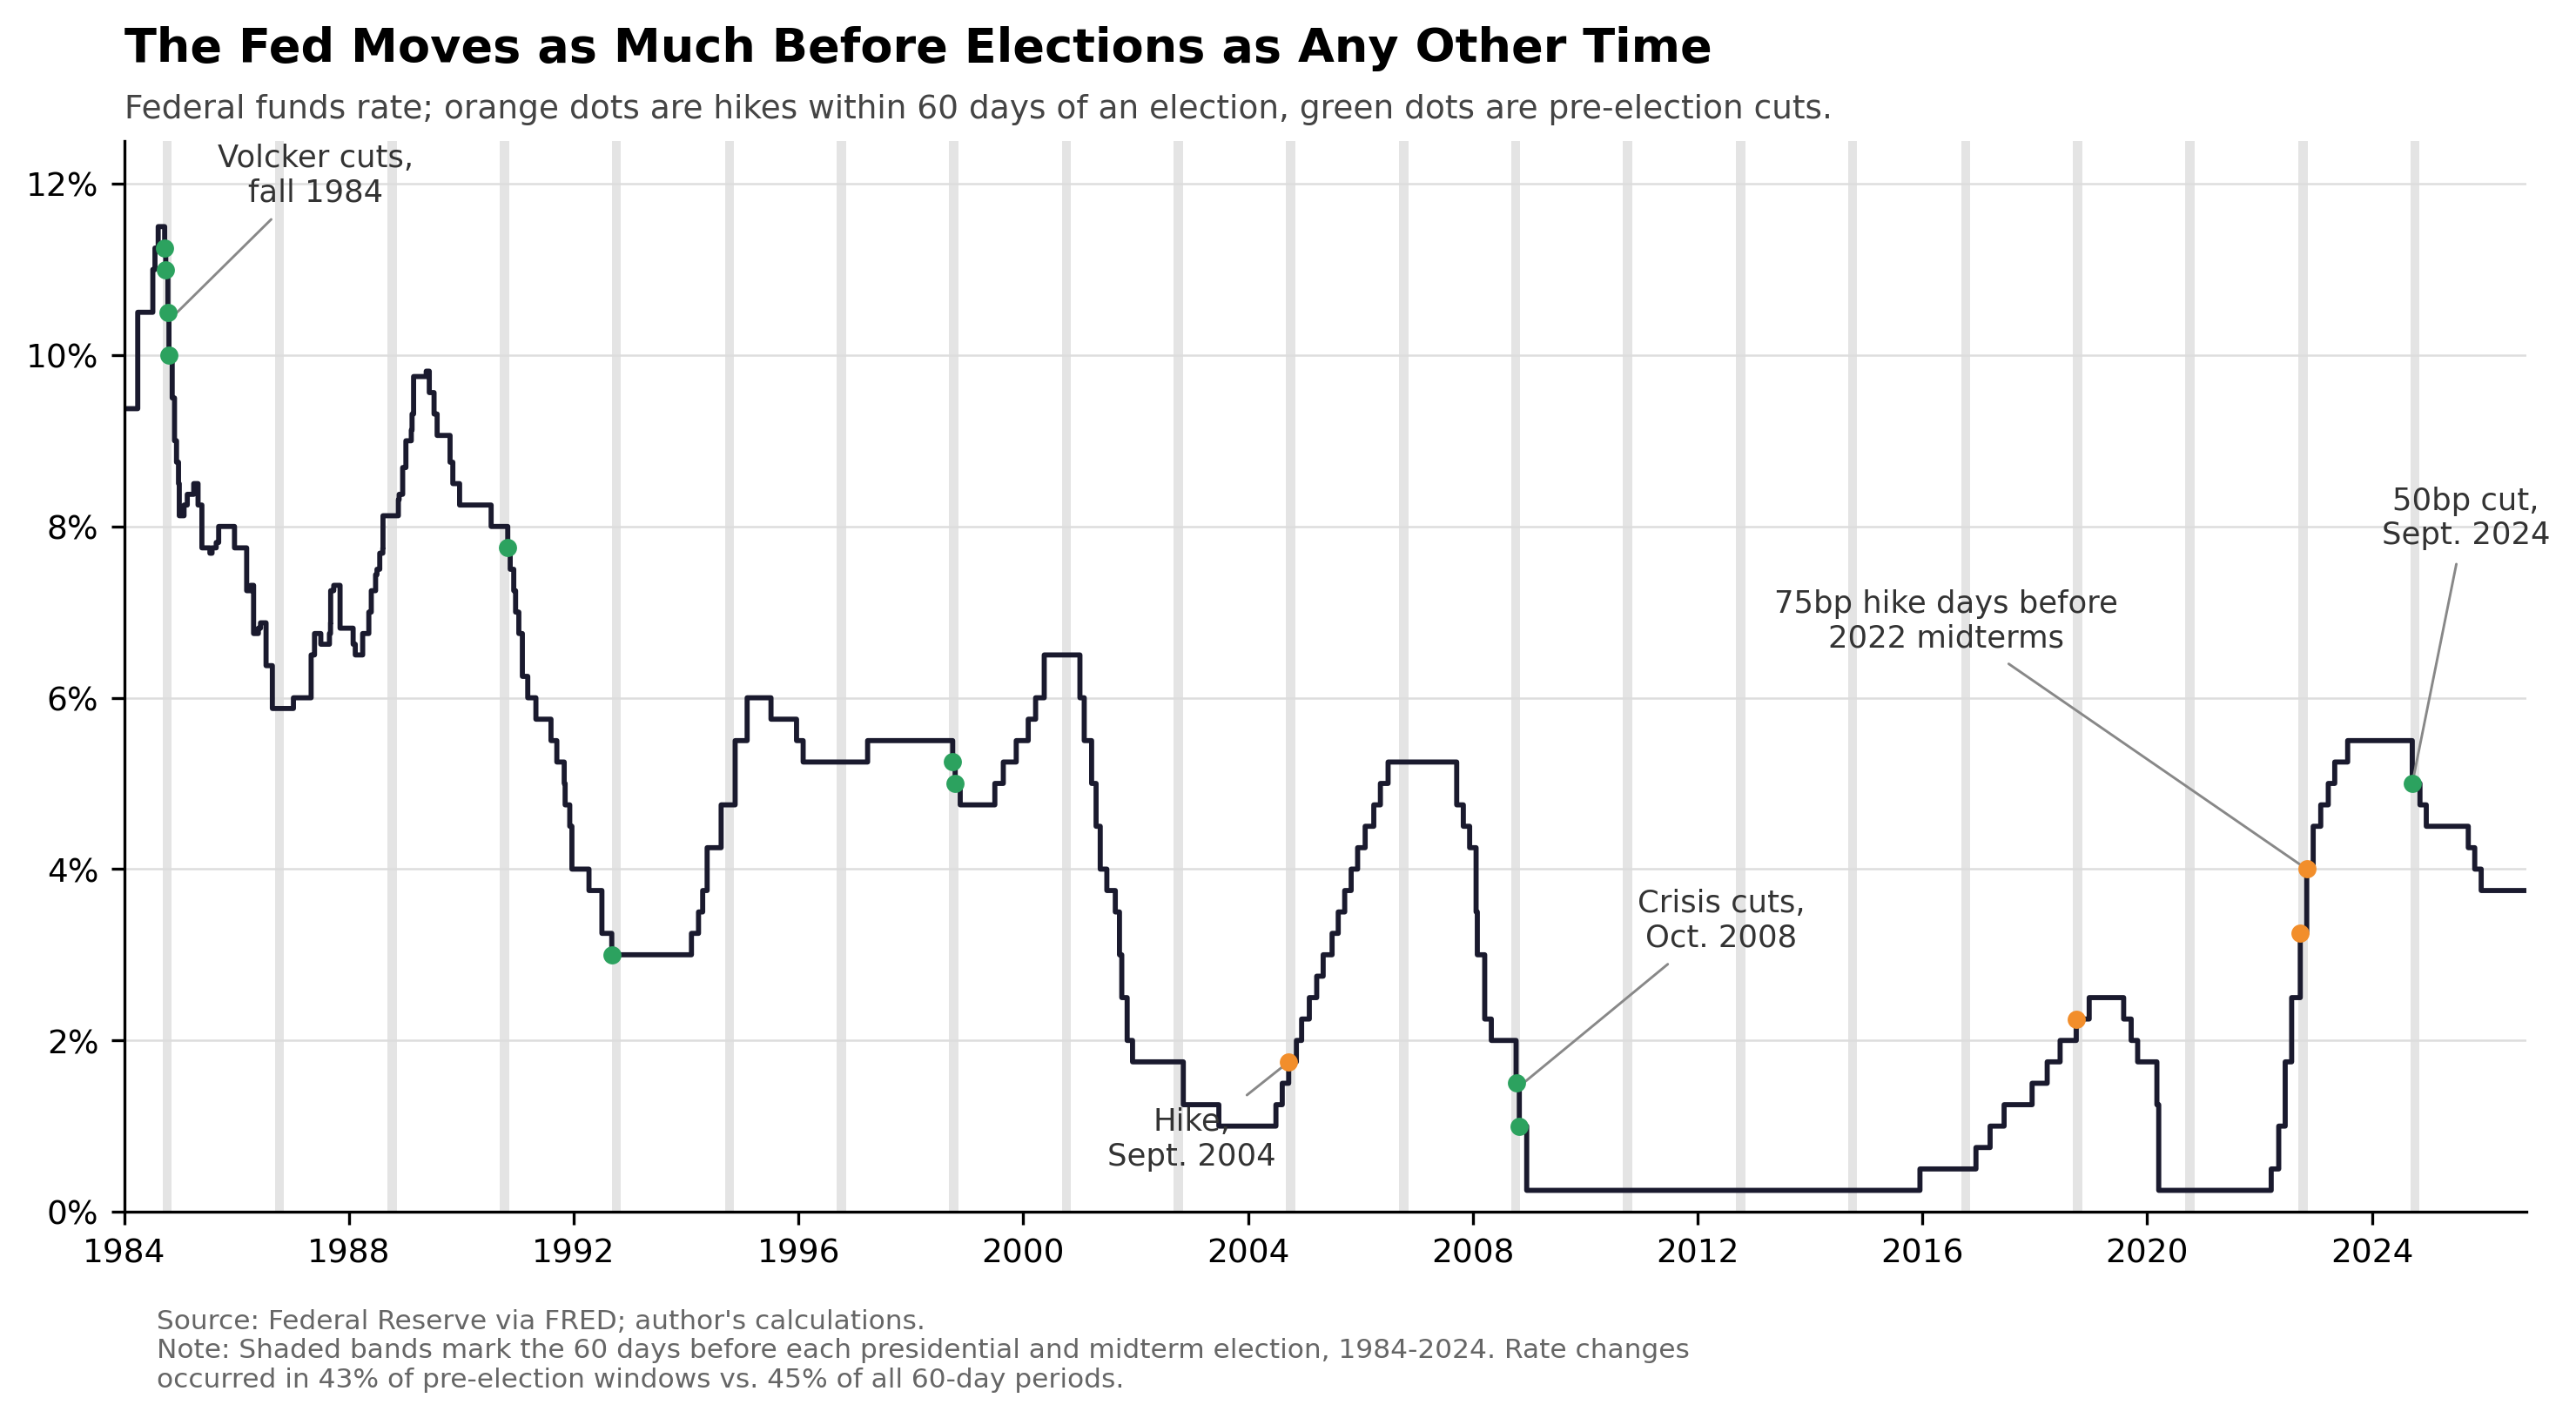
That’s not an argument to hike either. The Fed must stick to its mandate and ground its decisions in economics, not politics. The historical record shows it has. From 1984 to 2024, the Fed changed rates in 43% of the 60-day windows before an election, versus 45% of all 60-day periods. The last time the Fed raised rates before an election was days before the 2022 midterms under Biden, and it cut rates before the 2024 election.
Warsh was Trump's pick for Fed Chair, but so far, I see no signs that politics is driving his leadership at the Fed. Powell was also Trump's pick, and their relationship soured quickly in Trump's first term. Furthermore, appeasement also doesn't work with this White House. Michael Barr stepped down as vice chair for supervision in early 2025 to avoid a fight, and the fights came anyway: the attempted firing of Lisa Cook that summer, then the Justice Department investigation of Powell this year. Delay past November, and an emboldened Trump comes back in December demanding more.
Nothing is a done deal until it’s done.
No matter the implied certainty in market pricing or the agreement among talking heads, a rate decision isn’t final until the FOMC votes. The Fed is under no obligation to avoid surprising markets. As I explained to AFP, if a majority decides this week that a hold is the most appropriate policy, the Fed will hold. But when the Fed surprises markets, it has to work extra hard to explain itself. The Fed has not done a great job explaining why it has held, particularly in July, and that opens a gap between what the Fed is thinking and what markets think the Fed is thinking.
If the Fed raises rates as expected, the dot plot released with the statement will offer some sense of how many more increases officials see as likely. The SEP is a snapshot, not a promise of what the Fed will do in October or December.
Warsh does not want to box the Fed into its future decisions. His initial approach was to say less. A better approach is to stress the conditionality. If inflation risks are what justify a hike, then an improvement in those risks is a reason not to hike again, and the Fed should say so.
In closing.
Anytime the Fed raises rates, it's consequential. Higher interest rates create direct costs for millions of Americans through borrowing and potentially indirect costs through a weaker labor market. It should never be done lightly, but it is the tool the Fed has to contain inflation. If inflation moves back down to 2% in the next year or two, it will not be due solely to the Fed. The Fed has a role to play, and it owes the public a clear account of that role. The July presser left too many questions unanswered. Wednesday cannot repeat that mistake.
The UST10 yield kissed 5.017% today, which invited significant buying, backing that yield to 4.95% for a quick trade profit, resulting in a ratcheting up to 5.001% then a close at 4.988%.
IMO, the bond market is signaling two things:
1) an acceptance of the Bessent audacious challenge that, "I am the house" with conviction.
2) an unequivocal rejection of the Trump inflationary economic policies, the toxin of which has now infested globally.
Maybe I'm ignorant, but I fail to see any link between not lowering the funds rate to Trump's threat to cut off trade with “some countries."
I can't wait to see his infuriated reaction to a 25 bps rate hike. It's great to see Trump angry. It would be just as great if voters get just as angry to ensure a blue tsunami at midterms.
Spot on Claudia!
The Committee will make the decision they deem best. I wouldn’t read much into the fact that a hold would be a shock to the futures markets. Those market prices have moved a lot in the last week with the inflation data which frankly wasn’t very hawkish or dovish IMO. We came into the quiet period with the members speaking and the market interpreting their comments as basically 50-50 so the whole market reaction is traders anticipating reaction functions from voters who are in the quiet period.
Warsh has spoken about wanting to break the “hall of mirrors” where the committee uses market prices to infer beliefs and optimal policy, but the market prices reflect endogenous beliefs about the committee’s choices. A hold would break this cycle. Before the last FOMC, I wrote about the FOMC communication policy and how a change from past market guiding practices could increase the term premium (see my substack)
That said, I do think a hike is in order, but it won’t be as contractionary as one might think. The long end of the curve has tightened considerably. There are real drivers, but I think we also have some Lorenzoni & Werning (2019) style slow runs on the high debt countries. In these types of cycles, a credible central bank matters a lot. I wouldn’t be at all surprised to see a hike in the policy rate combined with a well worded statement and PC arrest the rise in long-term yields and flatten the curve. This would be a wash in terms of tightening financial conditions.
I think you are completely correct to note the SEP and the Chairs PC will matter a lot. Here, ironically Trump’s lobbying and threats may help him achieve his goals in a way he doesn’t realize. If the committee votes to raise and the Chair gets questions about independence it’s a perfect opportunity to reiterate that the FOMC is independent. A claim that will be more credible after a rate increase in the wake of Trump’s lobbying. If the market believes the Fed is credibly committed to the nominal anchor and will ignore politics the Fed ironically may not have to raise rates as much as they would in the absence of this market trust.
Finally, a word about inflation. Even though the probability of a rate hike in September has shot up in the past week, the market’s beliefs about inflation are well anchored. You can see this in the futures prices for the policy path that increased only slightly for June27 onward. In other words, the total amount of rate increases didn’t change much, just the timing of them. Also, the spread around the path implied by SOFR options has decreased since the inflation reports. Investors are more confident in their beliefs about the policy path!